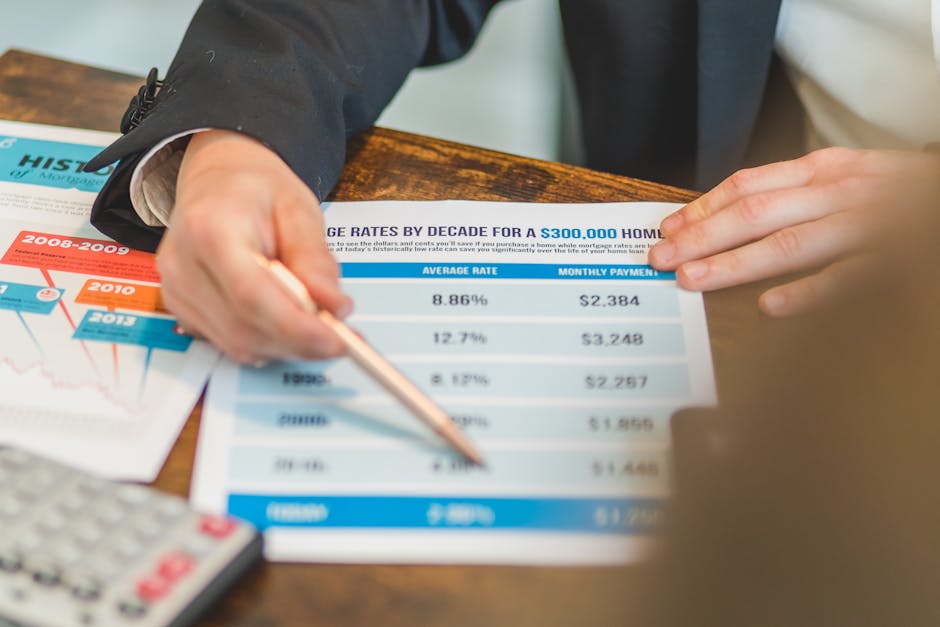
Central bank rate decisions reach mortgage and loan rates unevenly, and the best-known number, a pass-through rate of roughly 70 to 80%, is a cross-study average rather than a figure for any household. This article sets out how interest rate decisions affect mortgage and loan rates through the figures we could source, what each measures and where it stops applying to UK or US borrowers.
Why this matters now
The Bank of England held Bank Rate at 3.75% on 17 September 2026 by a 6–3 vote, with three members favouring a rise to 4%. In the US, Bankrate reported in mid-2026 that the Federal Reserve had held after three cuts in late 2025.
How a decision moves through the system
The Fed sets its federal funds rate mainly by adjusting the interest it pays on reserves and its overnight reverse repo rate. Those changes hit bank funding costs first. Lending rates follow more slowly, because each product reprices on its own schedule. The ECB's 2025 Economic Bulletin separates pass-through to new loans from pass-through to the average rate on the existing stock, which depends on maturities, fixation periods and repayment rates. It covers the euro area only, so it explains the mechanism rather than UK or US timing.
The headline pass-through figure: roughly 70 to 80%
A 2025 meta-analysis published by Springer in a Palgrave journal puts the long-run average pass-through of policy rates to bank lending rates at about 70%, and says it is often incomplete. An arXiv meta-analysis reports a coefficient near 0.8. The two estimates differ, and both pool studies across emerging and advanced economies. Neither is a UK or US household figure.
Consumer loans pass through less
The Springer analysis puts consumer-lending pass-through about 19% lower than other loan categories. The arXiv study finds lower pass-through for consumer and long-term loans than for short-term corporate loans. The direction is consistent across the two; the size of the gap is less certain. A 19% gap between averages does not mean your card will move 19% less than your mortgage. Lender pricing, product terms and local rules set your rate.
Why country-level studies do not transfer
An IMF working paper on Brazil found unsecured consumer loans, including cards and non-payroll personal loans, peaked at about 80% pass-through after four months. Payroll-deducted loans peaked at about 40% after ten months, which the authors attribute to interest-rate caps. In one case, a cap on pension-backed loans stayed at the same monthly level while the policy rate rose 5.5 percentage points. A Czech central bank study found pass-through to consumer lending rates unreliable, while SME rates passed through completely. These are single-country results and do not carry over to US or UK borrowers.
Credit cards: the prime rate and the APR problem
CNBC reported in January 2026 that credit cards are pegged to the prime rate, which sits about 3 percentage points above the federal funds rate. Yahoo Finance quotes an analyst who expects existing cardholders to see a quarter-point cut within a month or two of a Fed move, while the average rate for new customers would probably move little. That is an opinion, not a measured estimate. Card averages also differ by source: LendingTree put the average APR at 23.79% in January 2026, according to CNBC, while Bankrate put the end-2025 average at 19.7%. Always name the source and date when you quote an APR.
Mortgages, HELOCs and variable debt
CNBC's September 2025 explainer says US mortgage rates are tied to Treasury yields and the economy, and most US borrowers hold fixed-rate mortgages. A cut leaves a fixed rate unchanged unless the borrower refinances or moves.
Why a US rate cut may not lower a mortgage rate
Bankrate reports three Fed cuts in late 2025 totalling 75 basis points, yet 30-year mortgage rates rose above 6.25% in March 2026 and reached the 6.5% range by June 2026. This comes from one aggregator's narrative and shows a pattern, not a tested cause.
HELOCs and variable-rate student loans
Bankrate says home equity rates tend to track the Fed benchmark, so HELOC rates should fall after a cut. Its forecast of HELOCs averaging about 7.3% in 2026 is one analyst's projection, not an observed rate. Private variable-rate student loans also move with the Fed; federal fixed-rate student loans do not.
UK figures: Bank Rate, the vote and the next decision
The Bank's September 2026 summary records the 17 September decision and vote described above. A secondary source gives 5 November 2026 as the next decision date. Check the Bank's own calendar before relying on it.
In its April 2026 Monetary Policy Report, the Bank said deposit rates and new corporate lending had changed little while mortgage rates rose, which it described as consistent with normal pass-through. It estimated that about 53% of mortgage holders would see payments rise, while about 25% of those who fixed at higher rates would see payments fall.
A HomeOwners Alliance page dated 19 October 2026 gives an average two-year fixed rate of 5.96%. It is a secondary source.
Are rate rises and cuts passed on equally?
The evidence is contested. The Springer meta-analysis reports possibly lower pass-through during easing than tightening. The Brazil IMF paper found no asymmetry between hiking and easing cycles. A Bank of Spain bulletin found mortgage pass-through weaker in expansions than contractions, but no significant asymmetry for consumer lending. These studies cover different markets, so none settles the question for the UK or US.
What the figures cannot tell you
Market expectations are forecasts, not outcomes. The HomeOwners Alliance says markets price around four UK rate rises by end-2027 and cites a Reuters poll in which most economists expect a November rise. We have not verified that poll. The biggest gap is US data: no primary estimate of household pass-through over 12 months was found, so US figures are analyst views or averages from different surveys.
Before acting, check which product you hold, whether it is fixed, tracker, variable or a card, and when it next resets. That, more than any average, decides how much of a rate decision reaches you.